 About Urh Social
 Terms of Service
 Privacy Policy
 Contact
Server Market Trends: AI and High-Performance Computing Drive Growth
Market Overview
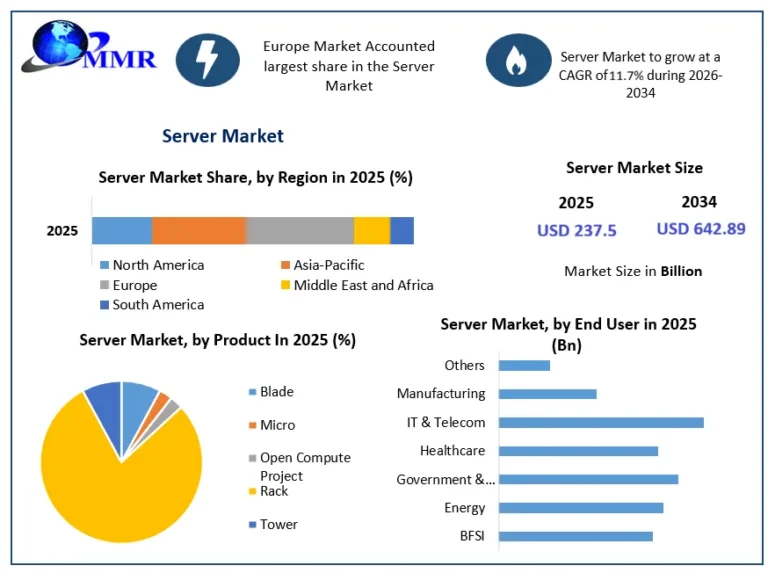
The Server Market is entering a high-growth phase as enterprises, cloud service providers, hyperscalers, and government organizations increase investments in digital infrastructure, artificial intelligence (AI), cloud computing, big-data analytics, and high-performance computing. According to the latest study by Maximize Market Research, the global server market was valued at approximately USD 237.5 billion in 2025 and is projected to reach USD 642.89 billion by 2034, registering a CAGR of 11.7% during 2026–2034. The increasing volume of data generated by connected devices, digital services, enterprise applications, and AI workloads is creating sustained demand for high-performance, scalable, secure, and energy-efficient server infrastructure.
Market Estimation, Growth Drivers and Opportunities
The rapid adoption of cloud services, enterprise digital transformation, Internet of Things (IoT), 5G, edge computing, virtualization, and generative AI is supporting server market expansion. Modern organizations require increasingly powerful infrastructure to process large datasets, host applications, operate databases, support real-time analytics, and deploy AI models. Data-center modernization is another important growth driver because organizations are replacing legacy infrastructure with high-density systems capable of supporting accelerated computing workloads.
Artificial intelligence is creating a particularly significant opportunity for server manufacturers. AI training and inference require large quantities of computing resources, including CPUs, GPUs, high-bandwidth memory, advanced networking, and sophisticated thermal-management systems. The growing deployment of AI applications across financial services, healthcare, manufacturing, telecommunications, government, and retail is therefore increasing demand for AI-optimized servers.
Energy efficiency is also becoming an important purchasing criterion. High-density AI servers generate substantially more heat than conventional enterprise systems, encouraging manufacturers to develop direct liquid cooling, advanced heat exchangers, improved power-management technologies, and more efficient server architectures. Opportunities are emerging for vendors that can combine high computing performance with lower power consumption, improved reliability, and reduced total cost of ownership.
Request To Free Sample of This Strategic Report ➤ https://www.maximizemarketresearch.com/request-sample/198992/
U.S. Market Trends and Investment
The United States remains a major center of server and AI infrastructure investment. In January 2025, Microsoft said it expected to invest approximately USD 80 billion in fiscal 2025 to develop AI-enabled data centers, with more than half of that investment expected in the United States. The Stargate project announced in January 2025 also outlined an intended USD 500 billion investment over four years in U.S. AI infrastructure, beginning with USD 100 billion of immediate deployment. In addition, the U.S. government issued an executive order in July 2025 intended to accelerate federal permitting for data-center infrastructure. Google separately announced major U.S. investments in cloud and AI infrastructure, including USD 9 billion in Virginia and USD 40 billion in Texas through 2027. These developments are supporting demand for servers, networking equipment, storage, power infrastructure, and advanced cooling technologies.
Market Segmentation – Largest Market Share
By Product, Rack Servers held the largest market share. Rack servers are widely used because they provide efficient space utilization, scalability, simplified management, and flexibility for high-density data-center deployments. They are particularly suitable for enterprises, cloud service providers, hyperscale facilities, and organizations handling growing AI and data-processing workloads. Their compatibility with high-performance CPUs, GPUs, networking components, and modern cooling systems makes rack-based infrastructure an important platform for next-generation computing environments.
Competitive Analysis
The competitive landscape includes global server manufacturers and infrastructure providers developing increasingly powerful systems for conventional enterprise computing as well as AI and HPC applications. Based on IDC's fourth-quarter 2025 worldwide vendor data, Dell Technologies, Super Micro Computer, IEIT Systems, Lenovo, and Hewlett Packard Enterprise (HPE) were the five leading named vendors by server revenue share. Dell held approximately 10.0%, Supermicro 9.3%, IEIT Systems 4.1%, Lenovo 4.0%, and HPE 3.1% in that quarter.
Dell Technologies continued expanding its AI infrastructure portfolio. Its fiscal 2025 server and networking revenue increased 54%, primarily due to growth in AI-optimized servers. During 2025, Dell also expanded PowerEdge-based AI infrastructure and introduced further AI Factory capabilities with NVIDIA, including enhanced server, networking, automation, and cooling solutions.
Super Micro Computer strengthened its position through high-density AI systems and liquid cooling. In 2025, the company introduced solutions based on NVIDIA Blackwell and AMD Instinct MI350 platforms and expanded direct-liquid-cooling technologies. Its systems are designed for AI training, inference, HPC, and large-scale data-center deployments, where thermal efficiency and computing density are increasingly important.
IEIT Systems continues to participate in the rapidly expanding Chinese and international server infrastructure ecosystem, particularly in cloud computing and accelerated computing. Increasing demand for domestic computing infrastructure and AI workloads in China provides an important market opportunity for the company and other regional server manufacturers.
Lenovo continues developing ThinkSystem infrastructure for enterprise, edge, cloud, and AI workloads. Its server portfolio is positioned to support organizations seeking scalable computing capacity as AI inference, analytics, virtualization, and hybrid-cloud deployments expand.
Hewlett Packard Enterprise introduced eight new ProLiant Compute Gen12 servers in February 2025, incorporating Intel Xeon 6 processors and capabilities focused on AI, security, performance, and energy efficiency. HPE also offered direct liquid cooling for selected systems, with the company highlighting improved performance per watt and substantial potential power savings. These innovations address the increasing need for efficient high-density computing infrastructure.
Regional Analysis
United States: The U.S. is a major global server market, supported by hyperscale cloud providers, AI developers, financial institutions, healthcare organizations, and large enterprises. Government initiatives aimed at expanding AI and data-center infrastructure, together with significant private-sector investment, are strengthening server demand.
United Kingdom: The UK is increasing investment in domestic computing infrastructure through its AI Growth Zones initiative. Government policy focuses on improving access to power, accelerating planning, and attracting private investment into AI-enabled data centers. More than £25 billion of private-sector data-center investment had been announced, supporting future demand for servers and related infrastructure.
Germany: Germany is a major European data-center location because of its connectivity, industrial base, and demand for cloud and AI services. Government initiatives emphasize energy efficiency, renewable power, waste-heat utilization, and expansion of data-center capacity. These measures create opportunities for energy-efficient servers and advanced cooling technologies.
France: France is strengthening its AI and digital infrastructure ecosystem through its national AI strategy and France 2030 program. In 2025, major data-center and AI infrastructure investments were announced, including large projects involving Brookfield, MGX, Bpifrance, Mistral AI, NVIDIA, and Prologis. Such investments are expected to increase demand for high-performance computing infrastructure.
Japan: Japan is encouraging semiconductor, AI, and data-center development to respond to rising computational demand. In February 2025, Japan's government advanced legislation intended to stimulate large-scale public and private investment in semiconductors and AI infrastructure, supporting the development of an ecosystem linking hardware, data centers, software, and AI technologies.
China: China represents an important server market due to its extensive digital economy, cloud infrastructure, and rapidly growing AI applications. Government initiatives in 2025 emphasized national data infrastructure, intelligent computing, large-scale computing clusters, and coordination of computing, electricity, networks, and data resources. This policy direction supports continued investment in domestic server and data-center capacity.
Request To Free Sample of This Strategic Report ➤ https://www.maximizemarketresearch.com/request-sample/198992/
Key Players
-
Dell Technologies
-
Super Micro Computer, Inc.
-
IEIT Systems
-
Lenovo Group Limited
-
Hewlett Packard Enterprise
-
IBM Corporation
-
Cisco Systems, Inc.
-
Fujitsu Limited
-
Huawei Technologies Co., Ltd.
-
Inspur Systems
-
ASUSTeK Computer Inc.
-
Oracle Corporation
Conclusion
The global server market is expected to experience sustained expansion through 2034 as AI, cloud computing, enterprise digital transformation, and data-center modernization reshape computing infrastructure requirements. The most significant opportunity lies in AI-optimized, high-density, energy-efficient server systems, particularly those incorporating advanced GPUs, high-bandwidth memory, fast networking, and liquid-cooling technologies.
The combination of growing data volumes and increasing AI workloads is likely to shift server purchasing toward performance-per-watt, scalability, reliability, and total cost of ownership rather than computing performance alone. Data-center operators are also seeking technologies that can accommodate higher rack power densities without proportionally increasing energy and cooling costs. Consequently, innovations in direct liquid cooling, modular rack-scale infrastructure, AI accelerators, efficient processors, and intelligent server management are expected to remain important growth areas. Companies capable of delivering integrated computing and cooling solutions while meeting the requirements of hyperscalers, enterprises, and sovereign AI initiatives will find substantial opportunities in the expanding global server market.
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
Contact Us
Maximize Market Research Pvt. Ltd.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
Phone: +91 9607365656
Email: [email protected]

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Russian
 Romaian
 Portuguese (Brazil)
 Greek