 About Urh Social
 Terms of Service
 Política de privacidade
 Contact
Protein-Fortified Noodles and Pasta Market Growth, Analysis Industry Outlook & Region Forecast Analysis By Fact.MR
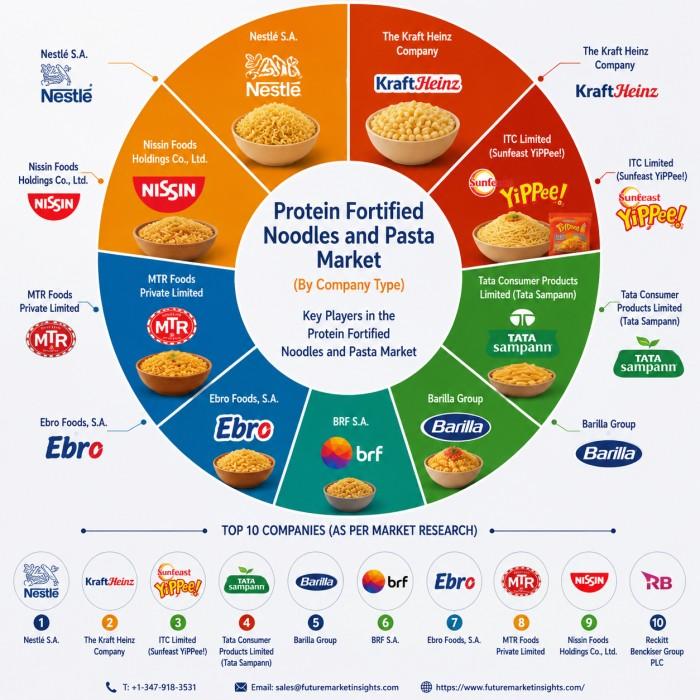
ROCKVILLE, MARYLAND , Sept 23, 2026 — The protein-fortified noodles and pasta market is projected to expand from USD 3.5 billion in 2026 to USD 6.9 billion by 2036, recording a compound annual growth rate of 7.0%. The category reached USD 3.3 billion in 2025 and is expected to generate USD 3.4 billion in added annual revenue between 2026 and 2036.
Get detailed market forecasts, competitive benchmarking, and pricing trends:
Key Findings
· Market value: USD 3.3 billion in 2025; USD 3.5 billion in 2026; USD 6.9 billion by 2036.
· CAGR: 7.0% from 2026 to 2036.
· Leading product segment: Protein-fortified pasta at 43.0% share in 2026.
· Leading protein source: Plant protein at 48.0% share in 2026.
· Leading distribution channel: Supermarkets & hypermarkets at 46.0% share in 2026.
· Leading end user: Retail consumers at 58.0% share in 2026.
· Leading claim: High protein at 51.0% share in 2026.
· Leading company: Barilla Group with 16.0% market share.
Note: Source materials reference both a 2025 value of USD 3.3 billion and a 2026 starting value of USD 3.5 billion; the forecast trajectory and 7.0% CAGR from 2026 to 2036 remain consistent across statements.
Growth Drivers
· Consumers seek higher protein intake within familiar dinner formats rather than limiting intake to bars, shakes, or sports-nutrition products.
· The International Food Information Council reported in July 2025 that 35% of Americans had increased protein intake over the prior year and that 56% prioritized protein at dinner.
· Manufacturers can raise protein content while preserving established sauces, cooking methods, portion habits, and family meal routines.
· Retailers merchandise protein-fortified products beside conventional pasta, gluten-free foods, and health-oriented meal solutions.
· Ready-to-cook and one-pot formats extend the category into convenience-led occasions.
· Hybrid formulations combine protein density with mainstream sensory cues and convenience.
Segment Analysis By Product
Protein-fortified pasta holds 43.0% share in 2026. Familiar shapes such as spaghetti, penne, and fusilli fit established sauces, cooking methods, portion habits, and family menus, lowering the behavioral cost of substitution. Manufacturers adjust wheat, pea, chickpea, lentil, egg, or dairy protein while preserving a recognizable bite. Other segments include protein-fortified noodles (instant noodles, ramen, udon), ready-to-cook protein meals (macaroni meals, pasta meal kits, noodle meal kits), and gluten-free protein pasta (legume-based, chickpea, lentil).
By Protein Source (Technology/Formulation)
Plant protein accounts for 48.0% share in 2026. Inputs include pea, soy, wheat, chickpea, lentil, and fava bean. These support wheat-based and gluten-free products and address overlapping high-protein, plant-forward, gluten-free, and clean-label needs. Animal protein (whey, egg, milk) and alternative protein (chickpea, lentil, fava bean) form additional categories.
By Application (End User and Claim)
Retail consumers represent 58.0% share in 2026, driven by household repeat purchase and normal pantry rotation. Sub-groups include fitness enthusiasts, health-conscious consumers, and families. Foodservice (restaurants, cafés, quick-service restaurants) and institutional buyers (schools, hospitals, corporate cafeterias) form secondary channels. High-protein claims hold 51.0% share in 2026; additional claim bands cover 15–20 g protein, above 20 g protein, and sports nutrition.
By Distribution Channel
Supermarkets & hypermarkets capture 46.0% share in 2026 through side-by-side comparison, promotions, and routine grocery traffic. Other channels include online retail, health food stores, and convenience stores.
Country-Level Growth Comparison
|
Country |
CAGR (2026– 2036) |
Commercial Condition |
|
United Kingdom |
7.6% |
Broad grocery reach and disciplined price architecture amid volume volatility and promotional sensitivity |
|
USA |
7.3% |
Protein-seeking households and national grocery distribution; regulated nutrient-content claims visible at shelf |
|
Germany |
7.0% |
Plant-forward and whole-grain eating patterns; conventional pasta quality remains the reference point |
|
France |
6.7% |
Legume, whole-grain, and front-of-pack nutrition cues (including Nutri-Score) |
|
Japan |
6.4% |
Localized noodle formats with precise texture, portioning, flavor compatibility, and convenience execution |
Regional coverage spans North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Competitive Landscape
Barilla Group leads with 16.0% market share, combining mainstream pasta familiarity with a Protein+ proposition based on durum wheat semolina and pea protein (20 g protein per 100 g). Other key providers include:
· Banza LLC
· Modern Table Meals
· Explore Cuisine
· Ancient Harvest
· The Only Bean
· Nestlé S.A.
· The Hain Celestial Group
· Chickapea Pasta
· Jovial Foods
Competition centers on claim compliance, sensory quality, convenient formats, and securing repeat grocery purchase.
Recent Developments
· April 2026: Banza LLC launched Wheat Protein Pasta and Wheat Protein Mac & Cheese (first expansion beyond gluten-free positioning). Semolina-and-chickpea pasta delivers 22 g of protein
per serving in rotini, penne, and elbows; products moved from TikTok Shop into major US grocery chains.
· February 2026: Chickapea Pasta launched a limited-time three-pack of Creamy

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek