 About Urh Social
 Terms of Service
 Политика конфиденциальности
 Contact
Invisible Aero-Conformal Arrays Market Advances at 14.8% CAGR as UK Posts 15.9% Growth in Stealth and UAS Integration
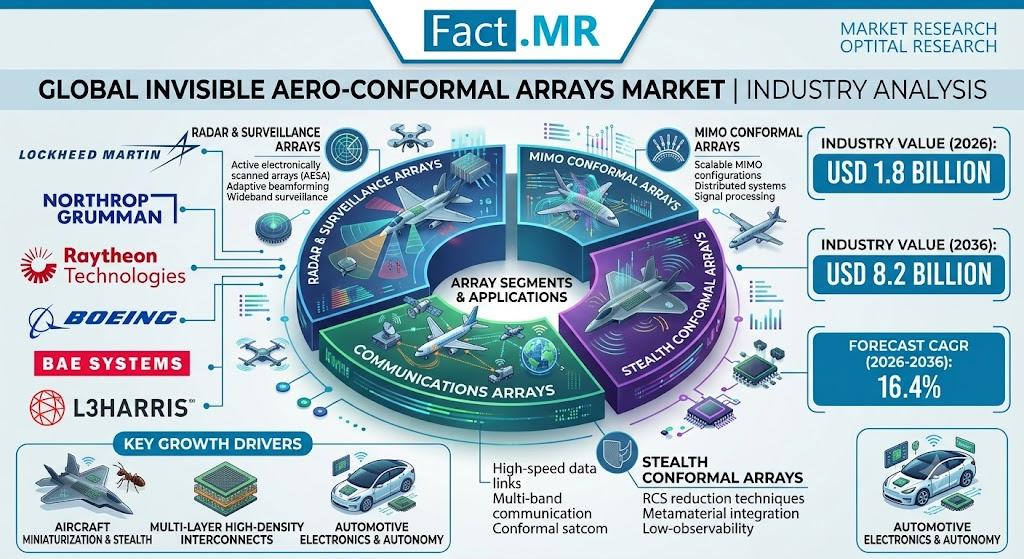
The global Invisible Aero-Conformal Arrays Market is projected to increase from USD 3.6 billion in 2026 to USD 14.3 billion by 2036, expanding at a 14.8% CAGR during the forecast period. The market crossed USD 3.1 billion in 2025, while the decade is expected to create an absolute opportunity of USD 10.7 billion.
Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.factmr.com/connectus/sample?flag=S&rep_id=16441
The market is being shaped by fighter integrators and unmanned aircraft teams seeking to move exposed antennas into low-profile conformal aperture layouts. Airframe engineers are looking for RF surfaces that preserve aircraft shape while leaving space for other mission hardware.
The shift also reflects growing requirements to combine radar, electronic warfare, communications, and sensing functions within aircraft-level architectures.
Aircraft Shape and RF Performance Move Closer Together
Traditional external antennas can affect aerodynamic integration, maintenance access, and aircraft surface design. Aero-conformal arrays provide another route by placing RF functions inside or against the aircraft structure.
The report identifies skin-embedded phased arrays as the leading aperture-integration segment, with a projected 36.0% share in 2026. These arrays give aircraft designers a direct route to low-profile sensing while supporting integration within shaped surfaces.
Conformal radome-integrated arrays remain relevant where protected RF windows are incorporated into nose or leading-edge structures. Printed structural arrays are suited to lighter UAS concepts, while metasurface-integrated apertures are gaining attention where flatter RF surfaces can reduce installation depth.
For program teams, qualification extends beyond RF performance. Curvature limits, thermal behavior, vibration resistance, repair access, and installed performance all become part of the aircraft integration process.
Fighter Aircraft Remains the Largest Platform Segment
Fighter aircraft is projected to account for 34.0% of market demand in 2026.
Stealth requirements, radar modernization, and electronic warfare upgrades are supporting the segment. UAS platforms follow as smaller aircraft require compact sensing systems with lower power and payload demands.
Missiles create narrower requirements for flush RF windows, while rotorcraft applications remain connected to surveillance and electronic protection where external antennas can affect drag and maintenance access.
Recent defense procurement also demonstrates the broader aircraft modernization environment. The U.S. State Department approved a possible USD 211 million Foreign Military Sale to Italy in June 2025 covering AMRAAM missiles and related equipment.
Radar Leads as Multifunction Missions Expand
Radar is anticipated to capture 34.0% share in 2026, supported by fire-control and threat-tracking requirements.
Electronic warfare follows as aircraft seek to detect or disrupt hostile emitters from shaped surfaces. SATCOM and data-link functions create additional applications where low-profile apertures can be integrated into aircraft structures.
The compactness requirement is also visible in radar development. RTX stated in September 2025 that its PhantomStrike radar weighs less than 130 pounds. The report cites this as an example of how compact AESA technology can fit UAS and light-aircraft integration requirements.
The market therefore extends beyond replacing a single antenna. Program teams are evaluating whether one aperture family can support several aircraft functions.
X-Band Holds a Leading Position
X-band is estimated to represent 31.0% share in 2026.
The band is linked to fighter radar requirements where compact apertures must deliver high-resolution sensing. Ku-band and Ka-band remain relevant for SATCOM and narrow-beam links, while S/C-band supports wider-area communications and selected lower-frequency sensing roles.
Multi-band arrays can provide another integration path where aircraft teams want sensing and communication capabilities within a common aperture family.
This multifunction approach is also creating opportunities for suppliers that can combine RF engineering with materials testing and aircraft-level integration evidence.
Qualification Remains a Key Market Constraint
The market's growth is supported by stealth aircraft sensor integration, multifunction radar and EW apertures, UAS programs, and compact X-band fire-control radar requirements.
The report identifies several opportunities:
- Retrofit kits for fifth-generation aircraft
- Conformal apertures for electronic attack aircraft
- Metasurface aperture research
- Exportable modular antenna families
At the same time, airframe qualification and testing represent a major restraint. Thermal and power limits can complicate integration, while embedded hardware can be harder to repair.
Classified performance evidence can also limit the amount of technical information available for external evaluation.
These factors can extend qualification timelines because the array must perform as part of the aircraft rather than as a standalone RF component.
Italy Leads the Country Growth Range
Italy is forecast to record the highest CAGR among the countries covered in the country comparison, at 16.7% from 2026 to 2036. The country's outlook is linked to fighter and airborne electronic attack integration.
The United States follows at 16.3%, supported by stealth aircraft upgrades and multifunction sensing. The UK is projected to advance at 15.9%, while France and Israel are forecast at 15.5% and 14.5%, respectively.
Italy's market activity includes airborne electronic warfare. L3Harris announced in July 2025 a USD 300 million contract from Italy to deliver two Gulfstream G550 aircraft provisioned for a modern electromagnetic warfare system.
In the United States, GAO reported in September 2025 that F-35 Block 4 modernization includes radar enhancements along with electronic warfare, communication, and navigation capabilities.
The UK is linking uncrewed aircraft development with future combat-air investment. GOV.UK reported in June 2026 that more than GBP 5 billion would be invested in drones and autonomous systems over four years.
France's outlook is tied to Rafale modernization and electromagnetic operations, while Israel's growth is connected to combat-aircraft renewal and long-range mission requirements.
Analyst Perspective
Shambhu Nath Jha, Principal Consultant at Fact.MR, states:
“Aero-conformal arrays draw attention because the antenna becomes part of the aircraft integration plan. Demand is expected to favor suppliers that combine RF design, materials testing and airframe fit evidence. Defense customers value low-profile arrays that keep radar or EW performance repeatable after installation.”
The report recommends that aperture suppliers document curvature limits, thermal behavior, and repair access before design freeze. Airframe integrators should test radome materials and embedded arrays together to maintain stable installed RF performance.
Defense electronics teams also need to coordinate radar and EW roadmaps when one aperture family supports multiple functions.
Competitive Landscape
The Invisible Aero-Conformal Arrays Market profiles Northrop Grumman, RTX, L3Harris, and BAE Systems.
Northrop Grumman participates through AESA fire-control radar and airborne sensing portfolios supporting fighter applications. RTX contributes through Raytheon's PhantomStrike compact AESA fire-control radar for uncrewed, light-attack, and fighter aircraft.
BAE Systems provides direct conformal-antenna coverage through its Silver Link portfolio. L3Harris is active in airborne electronic warfare integration, including work supporting Italy's G550 electromagnetic-warfare aircraft.
Across the competitive environment, supplier differentiation is linked to RF performance, aircraft integration, qualification evidence, thermal behavior, and compatibility with mission systems.
Read the full Invisible Aero-Conformal Arrays Market report: https://www.factmr.com/report/invisible-aero-conformal-arrays-market
Market Scope and Methodology
The Invisible Aero-Conformal Arrays Market covers low-profile RF apertures integrated into aircraft skins, radomes, structural panels, and low-observable surfaces. The scope includes skin-embedded phased arrays, conformal radome-integrated arrays, printed structural arrays, transparent or low-observable arrays, and metasurface-integrated apertures.
Applications include radar, electronic warfare, SATCOM, data links, navigation, and sensing across fighter aircraft, UAS, missiles, rotorcraft, and high-speed aircraft.
The analysis covers North America, Western Europe, Eastern Europe, Middle East & Africa, and Asia Pacific, with country-level analysis of Italy, the USA, UK, France, and Israel.
Fact.MR's analysis draws on 120+ sources, 35+ company portfolios, 25+ countries, and more than 20 industry interviews. Primary research covers manufacturers, technology developers, service providers, distributors, end users, and subject-matter experts. Desk research includes government publications, company filings, trade data, technical studies, industry associations, standards, and policy sources.
Other Related Reports:
https://www.newstrail.com/interactive-expo-displays-market-s/
https://www.newstrail.com/womens-t-shirts-market-forecast/
About Fact.MR
Fact.MR is a market research and consulting firm providing syndicated and custom research across aerospace and defense, technology, automotive, chemicals, healthcare, food, and other industries. Its research combines primary interviews, secondary research, market modeling, and data validation to support business and strategic decisions.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Romaian
 Portuguese (Brazil)
 Greek