 About Urh Social
 Terms of Service
 سياسة الخصوصية
 Contact
U.S. Defense Market Outlook: Trends and Growth Forecast (2026-2034)
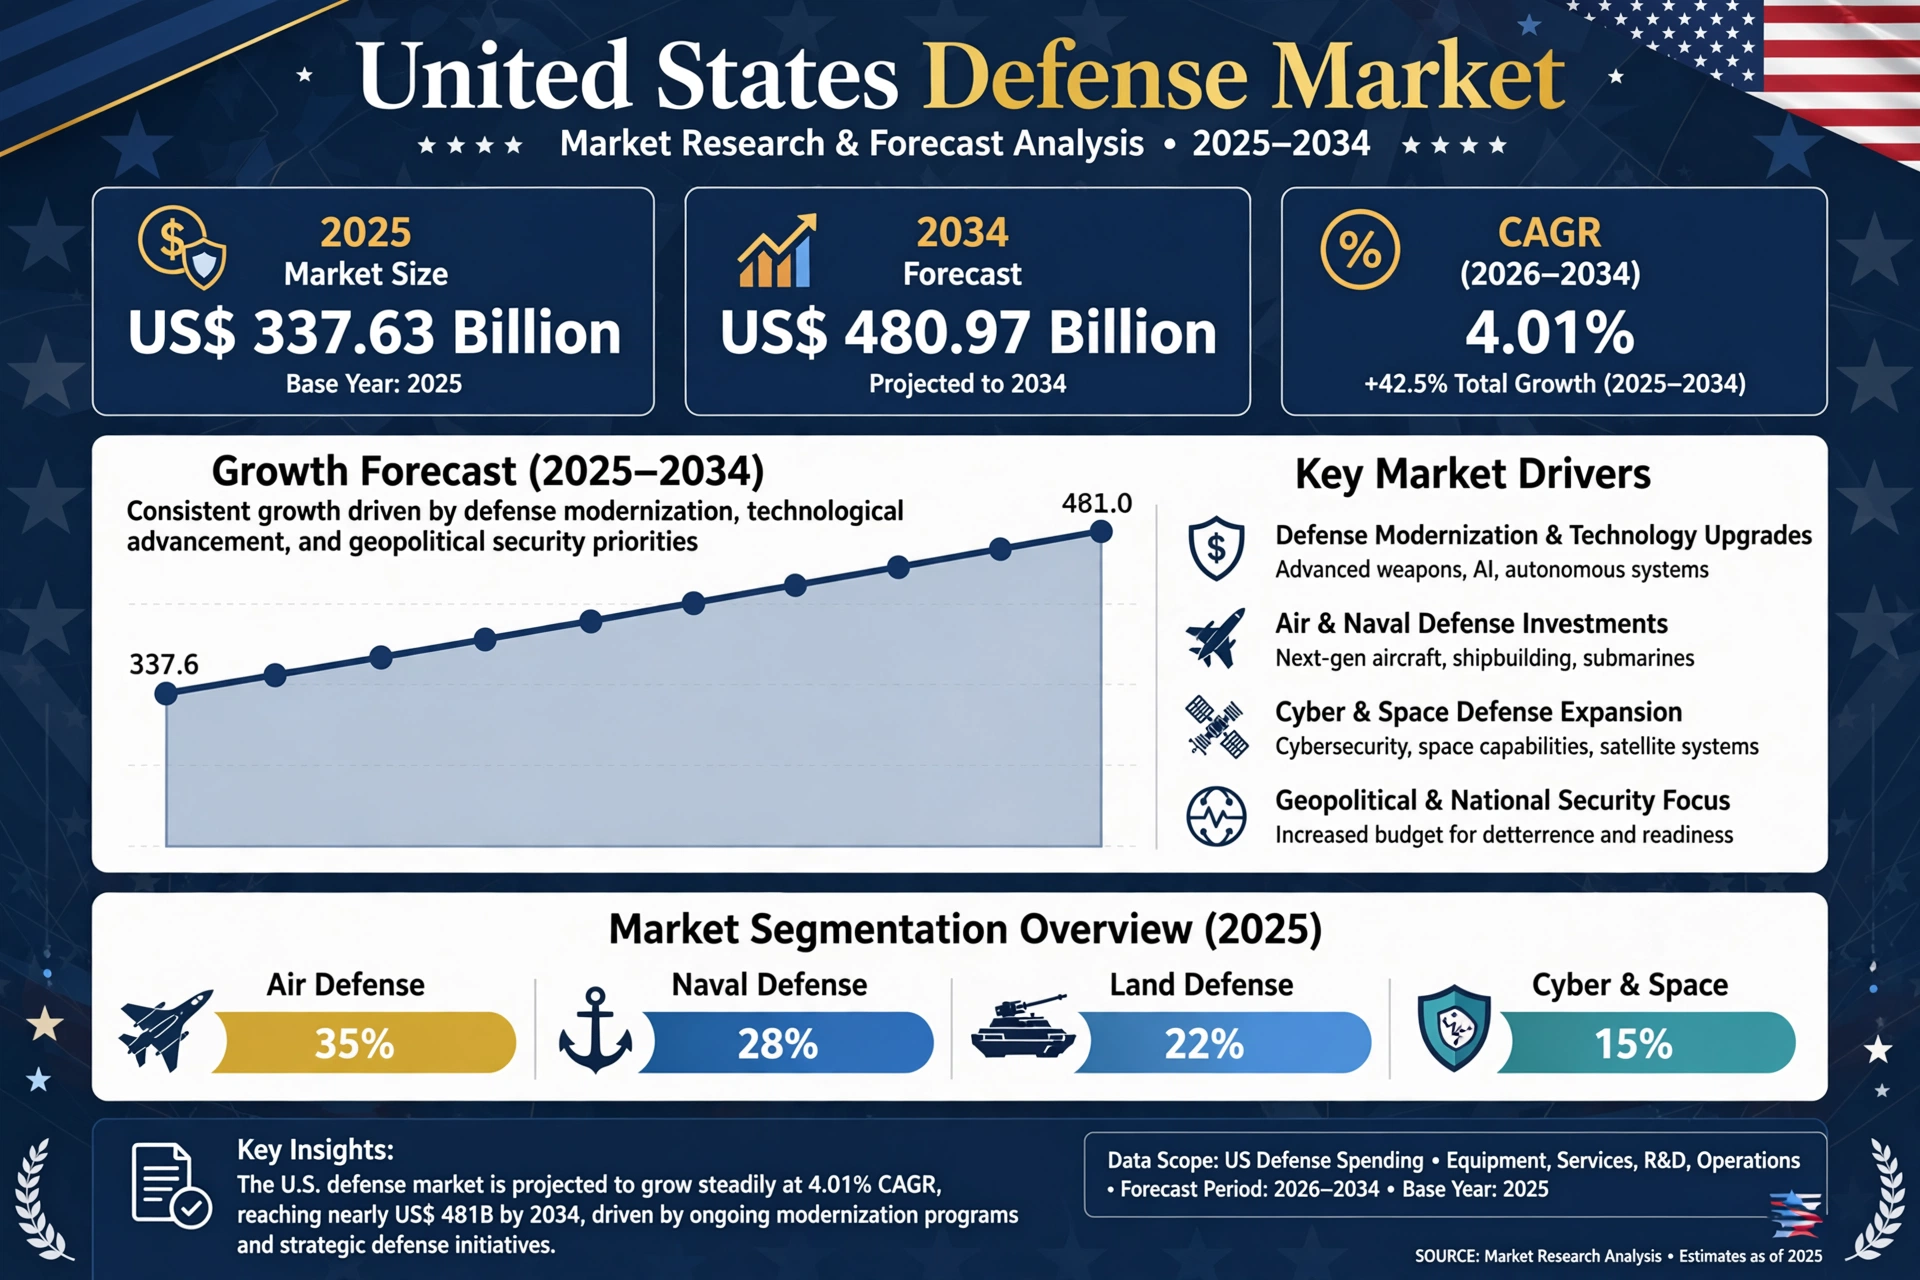
The United States defense sector stands as the most formidable and technologically advanced military ecosystem globally. Supported by a robust industrial base, consistent government investment, and an imperative to maintain strategic overmatch, the sector is entering a period of sustained expansion. According to recent analysis by Renub Research, the United States Defense Market is projected to grow from US$ 337.63 billion in 2025 to US$ 480.97 billion by 2034, expanding at a steady CAGR of 4.01% during the forecast period.
This growth is not merely a product of budgetary increases; it reflects a fundamental shift in military strategy. As the U.S. pivots from counter-insurgency operations toward "Great-Power Competition," the defense industrial base is being tasked with rapid modernization, the integration of autonomous systems, and the hardening of national infrastructure against multi-domain threats.
The Strategic Landscape: Industry Overview
The U.S. defense industry is a complex nexus of government procurement agencies, tier-one aerospace giants, and agile technology startups. It encompasses critical domains including aerospace platforms, naval supremacy, land-based maneuver systems, and the rapidly expanding realms of cybersecurity and space-based intelligence.
Modern military strategy now prioritizes "interoperability"—the ability for different platforms, from drone swarms to aircraft carriers, to communicate instantaneously via secure, AI-driven networks. This has shifted procurement priorities from simple hardware replacement to the integration of C4ISR (Command, Control, Communications, Computers, Intelligence, Surveillance, and Reconnaissance) systems. As geopolitical tensions rise, the U.S. Department of Defense (DoD) is actively leveraging the National Defense Authorization Act (NDAA) to accelerate the transition of laboratory-tested prototypes into frontline operational assets.
Primary Growth Drivers
Several structural and geopolitical factors are fueling the projected rise in defense spending through 2034.
1. Rapid Fielding Pathways (FY24 NDAA)
The bureaucracy of traditional defense acquisition—often spanning a decade from concept to deployment—is being bypassed. The FY24 NDAA provides commanders with "Rapid Fielding Pathways," allowing up to US$ 100 million annually per service for technologies that can be operationalized within 24 months. This has empowered Special Operations Command to move from requirement to contract award for counter-UAS (Unmanned Aircraft Systems) and AI-enabled ISR in as little as 15 days.
2. Modernizing Legacy Platforms
The U.S. military is currently managing fleets with an average age of three to four decades. Platforms such as the KC-135 tanker and the DDG-51 destroyer are reaching their mechanical limits, driving up maintenance costs. Consequently, the DoD is prioritizing a cycle of recapitalization. Significant investments, such as the US$ 1.381 billion grant to Northrop Grumman in early 2025 for the Integrated Battle Command System (IBCS), highlight the focus on keeping existing assets relevant through superior software and sensor suites.
3. Re-Prioritizing Multi-Domain Dominance
China’s "Anti-Access/Area-Denial" (A2/AD) posture in the First Island Chain has forced the U.S. to rethink force projection. The military is now shifting toward "stand-in forces"—units capable of operating within contested environments. This is exemplified by the Air Force's Next Generation Air Dominance (NGAD) program, including the F-47 fighter, which emphasizes stealth, long-range endurance, and the ability to operate in electromagnetically jammed environments.
Market Challenges: Innovation vs. Complexity
Despite significant funding, the defense sector faces systemic hurdles that could temper growth if left unaddressed.
-
Financial Pressures: The sheer cost of next-generation programs is staggering. Budgetary constraints, combined with the "cost-plus" nature of some large-scale contracts, often lead to project overruns that strain the procurement pipeline.
-
Supply Chain Resilience: The defense manufacturing network relies on thousands of global suppliers. Disruptions—whether due to regional instability or material shortages—can ground major production lines.
-
Technological Integration: Retrofitting legacy systems with modern AI and cyber-defenses is technically fraught. Ensuring that new software patches or autonomous upgrades do not compromise the physical security of a platform remains a primary engineering challenge.
Regional Hubs of Defense Innovation
The U.S. defense market is geographically concentrated in states that provide the synergy of high-tech research, manufacturing, and military operational bases.
California: The Innovation Engine
California leads in the "Silicon Valley of Defense." Home to major aerospace contractors and specialized tech firms, the state is the epicenter for space exploration, satellite constellations, and AI-driven military software.
Texas: The Manufacturing Powerhouse
Texas serves as a critical hub for large-scale production. With expansive military installations and heavy concentrations of aircraft and missile manufacturing facilities, the state is essential for land-based and aviation procurement.
New York & Florida: Strategy and Operations
New York’s influence is centered on cybersecurity, intelligence analytics, and communication systems, leveraging the state’s high density of top-tier academic research institutions. Florida, conversely, is the gateway for maritime and space defense, hosting vital naval facilities and commercial launch sites that support national security space missions.
Competitive Landscape and Recent Developments
The market remains dominated by established "Primes" that provide the backbone of U.S. military capability. Recent strategic moves include:
-
Missile Defense: In January 2026, Lockheed Martin and the DoD finalized a landmark agreement to more than triple the production of PAC-3 Missile Segment Enhancement units, signaling a massive scale-up in air defense readiness.
-
Autonomous Systems: In September 2025, the U.S. Navy awarded multiple contracts to a coalition of firms—including Anduril, Boeing, and Northrop Grumman—to develop Collaborative Combat Aircraft (CCA). These drones are designed to act as "loyal wingmen" to manned fighters, extending the reach and survivability of air operations.
-
Modular Systems: General Dynamics is currently deploying CMOSS (Modular Open Suite of Standards) systems for the U.S. Army, allowing vehicles to be upgraded with "plug-and-play" electronics rather than undergoing full overhauls.
Future Outlook (2026–2034)
The U.S. defense market is shifting toward a distributed, software-defined force. Over the next decade, we expect a reduced reliance on massive, monolithic platforms in favor of modular, attritable, and autonomous systems. Companies that can successfully integrate commercial-grade AI into military-grade hardware will define the market leaders of the 2030s.
Frequently Asked Questions (FAQs)
1. What is the forecast size of the U.S. defense market by 2034? The market is expected to reach US$ 480.97 billion by 2034, growing at a CAGR of 4.01% from 2026.
2. What are the primary drivers of U.S. defense spending? Growth is primarily driven by the need to modernize Cold War-era equipment, the shift toward Great-Power Competition, and the rapid adoption of AI, autonomous drones, and C4ISR technologies.
3. What is the "Rapid Fielding Pathway" in the FY24 NDAA? It is a legislative mechanism that allows military services to bypass traditional, slow procurement cycles to field emergent technologies within 24 months.
4. Why is the U.S. focusing on "Multi-Domain Dominance"? To counter A2/AD (Anti-Access/Area-Denial) strategies employed by near-peer adversaries, the U.S. must ensure forces can operate seamlessly across air, land, sea, space, and cyber domains simultaneously.
5. Which U.S. states are most significant for defense production? California (tech/space), Texas (manufacturing/aircraft), New York (cyber/intelligence), and Florida (naval/aerospace) are the leading states in the U.S. defense ecosystem.
6. What are "Collaborative Combat Aircraft" (CCA)? CCAs are unmanned, AI-enabled drones designed to fly alongside manned fighter jets, providing reconnaissance, electronic warfare, or weapons-delivery capabilities in high-risk zones.
7. How are high procurement costs affecting the industry? Rising costs are forcing a pivot toward modular and open-standard systems, which allow for cheaper, faster upgrades compared to replacing entire legacy platforms.

 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek