


 About Urh Social
 Terms of Service
 Privacy Policy
 Contact
The Cashless Future: Global Digital Payment Market Size, Trends, and Strategic Forecast (2026–2034)
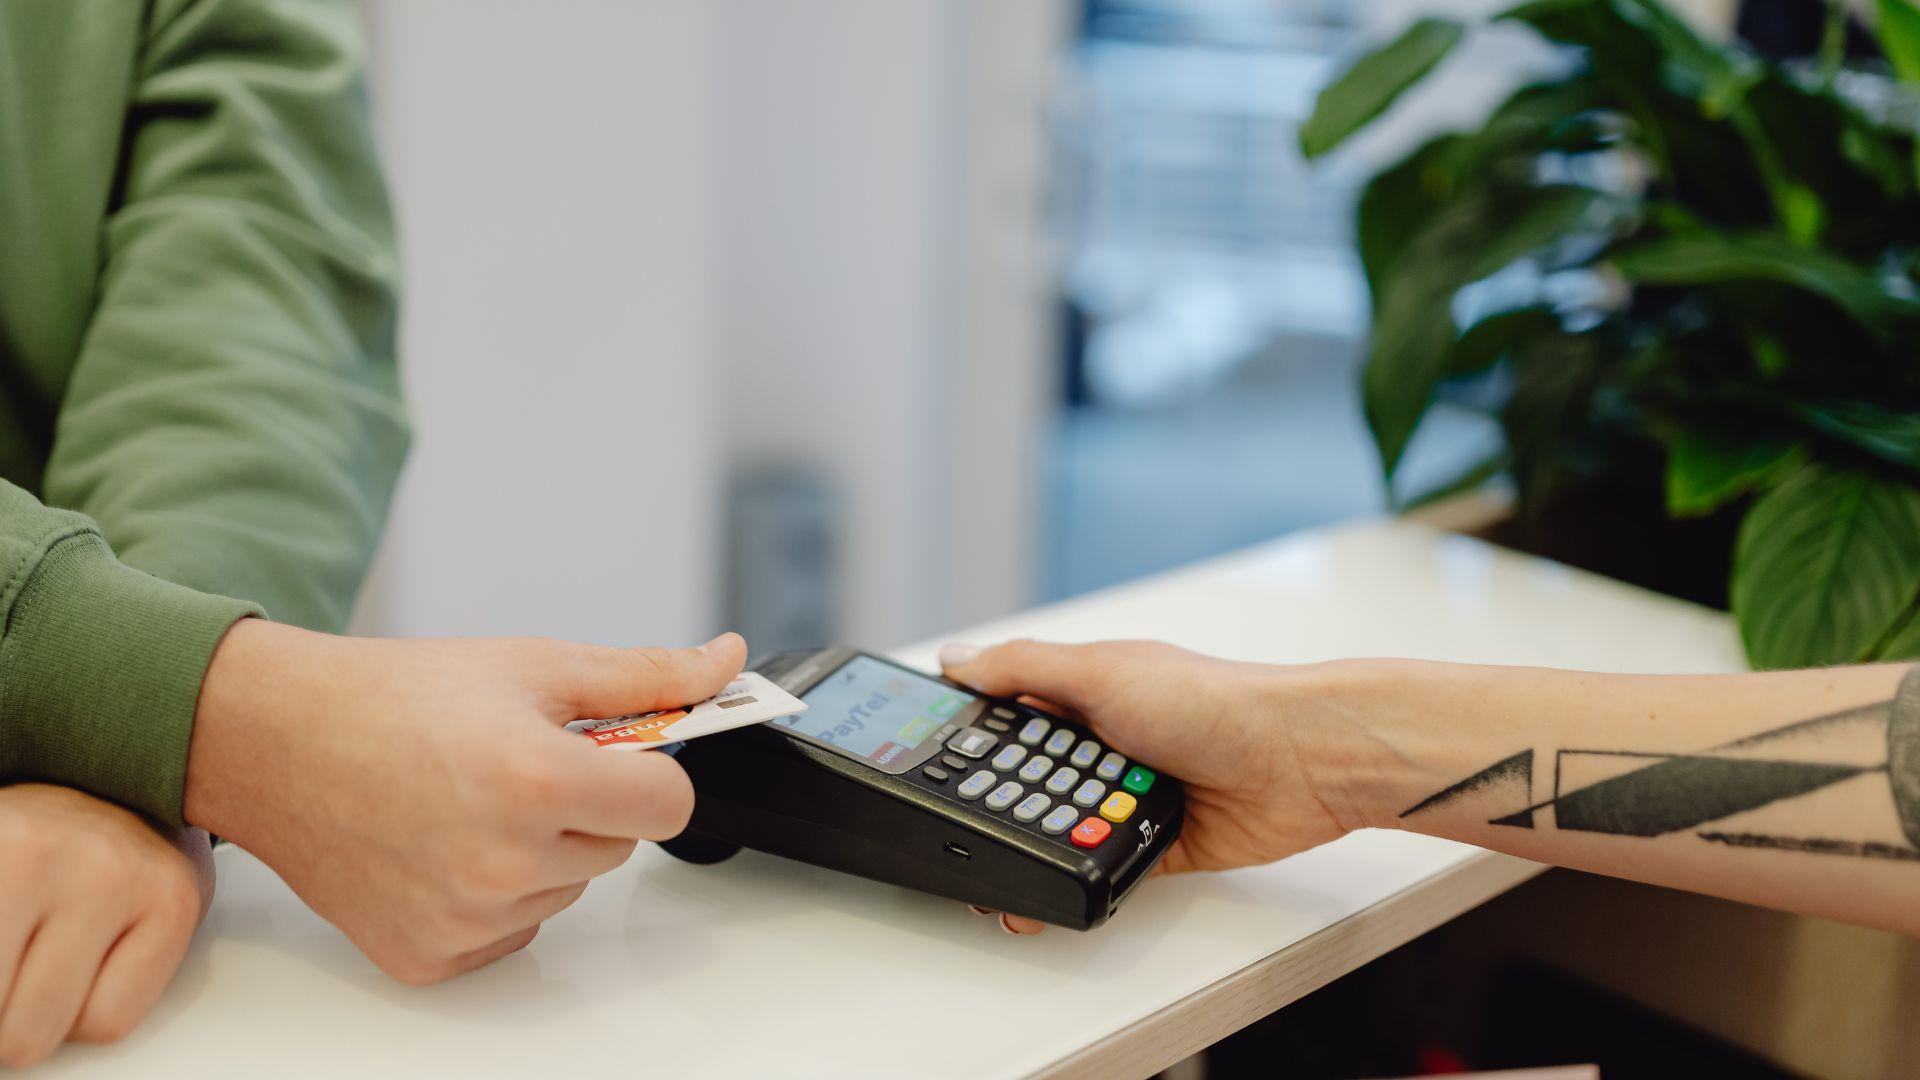
The global financial landscape is undergoing a definitive transition from physical currency to digital-first ecosystems. This shift is powered by the convergence of high-speed mobile connectivity, robust cybersecurity protocols, and a fundamental change in consumer behavior toward instant, frictionless transactions.
According to market analysis, the Global Digital Payment Market is poised for exponential growth, expected to climb from US$ 119.83 billion in 2025 to US$ 446.6 billion by 2034, representing a powerful CAGR of 15.74% throughout the forecast period of 2026–2034.
1. Digital Payment Industry Overview
Digital payments—encompassing mobile wallets, QR codes, contactless cards, and account-to-account (A2A) transfers—have become the nervous system of modern commerce. By replacing cash with electronic authentication (NFC, biometrics, and tokenization), the industry has successfully reduced the friction inherent in traditional banking.
The Core Pillars of Growth:
-
Technological Maturity: The adoption of tokenization and multi-factor biometric authentication has significantly bolstered consumer confidence.
-
Government-Backed Ecosystems: Nations are actively promoting "cashless" economies to increase tax transparency and financial inclusion.
-
Omnichannel Demand: Businesses are no longer separating online and offline retail; they are integrating unified payment gateways that allow consumers to pay seamlessly regardless of the channel.
2. Strategic Growth Drivers
A. Technological Innovation and Platform Scaling
Modern payment gateways are leveraging AI-driven fraud prevention and cloud-native APIs to offer merchants instant onboarding.
Example: PayPal’s launch of PayPal Complete Payments (PPCP) in Hong Kong serves as a template for the industry, enabling merchants to accept a vast array of payment methods (Google Pay, Alipay, Visa, Mastercard) through a single, streamlined integration.
B. Strategic Consolidation and Infrastructure Investment
The market is consolidating as global giants acquire local processors to gain immediate regional footprint. A prime example is Visa’s acquisition of Prosa in Mexico, which provides the infrastructure needed to harmonize digital payment standards across Latin America, effectively reducing market fragmentation.
C. The Rise of Mobile-First Commerce
In emerging economies, the smartphone is the only point of entry to the financial system. The development of advanced mobile SDKs has revolutionized this space.
-
Efficiency Gains: Innovations like PayU’s mobile app SDKs have demonstrated the ability to increase transaction success rates by up to 56%, proving that optimizing the user interface is just as critical as the backend security.
3. Market Challenges: The Balance of Trust and Speed
-
Cybersecurity & Fraud: As the market grows, so does the sophistication of bad actors. Phishing, SIM-swapping, and account takeovers are constant threats. Companies are forced to invest heavily in AI-based threat detection to ensure that security does not come at the cost of "checkout speed"—the industry’s most valued metric.
-
Regulatory Complexity: Global providers face a patchwork of data localization and KYC (Know Your Customer) laws. Balancing these local regulatory requirements with the need for a global, interoperable standard remains the primary hurdle for international expansion.
4. Key Regional Insights
5. Segment Spotlight: The Enduring Role of Cards
Despite the explosive rise of mobile wallets, the Cards Market remains an essential pillar. Cards provide a level of global acceptance and security that is currently difficult for new entrants to replicate. Rather than being replaced, cards are being "digitized"—tokenized and stored within mobile wallets—to provide the best of both worlds: the reliability of the card network and the convenience of the smartphone.
6. Strategic Forecast (2026–2034)
Market Growth Projection (US$ Billions)

2025: $119.83 B
--------------------------------------------------
2034: $446.60 B

CAGR: 15.74%
The future of digital payments lies in Embedded Finance and Real-Time Settlement. By 2034, the concept of "waiting" for a payment to clear will likely be obsolete, as instantaneous, secure, and cross-border digital transactions become the global standard for both consumers and businesses.
7. Frequently Asked Questions (FAQs)
Based on industry insights provided by Renub Research
Q1: What is the projected valuation of the global digital payment market by 2034?
A1: The market is expected to reach US$ 446.6 billion by 2034.
Q2: What is the growth rate (CAGR) expected for this market?
A2: The market is forecast to expand at a CAGR of 15.74% between 2026 and 2034.
Q3: Which technologies are primarily responsible for the increase in payment security?
A3: Key technologies include tokenization, biometric authentication, NFC, and AI-driven fraud detection systems.
Q4: Why are companies like Visa and PayPal acquiring smaller local processors?
A4: These strategic moves allow them to widen their global footprint, adopt local processing standards, and gain the necessary infrastructure to roll out advanced digital solutions in emerging markets.
Q5: What impact has India’s UPI had on the global market?
A5: India’s UPI has set a global standard for real-time payment infrastructure, handling over 80% of India's digital transaction volume and proving that scalable, low-cost real-time systems can dominate a massive market.
Q6: What is the main challenge for companies expanding globally in this sector?
A6: Regulatory fragmentation—specifically varying data localization laws, KYC/AML processes, and cross-border settlement rules—creates significant operational complexity.
Q7: Is the cards market losing relevance due to mobile wallets?
A7: No. Cards remain a core pillar of high-value and cross-border transactions; they are currently being integrated into mobile wallets (digitized) to remain a critical part of the modern, contactless payment experience.

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
