


 About Urh Social
 Terms of Service
 سياسة الخصوصية
 Contact
India Fertilizer Market Reaches US$ 44.62B; Set for Dramatic Expansion
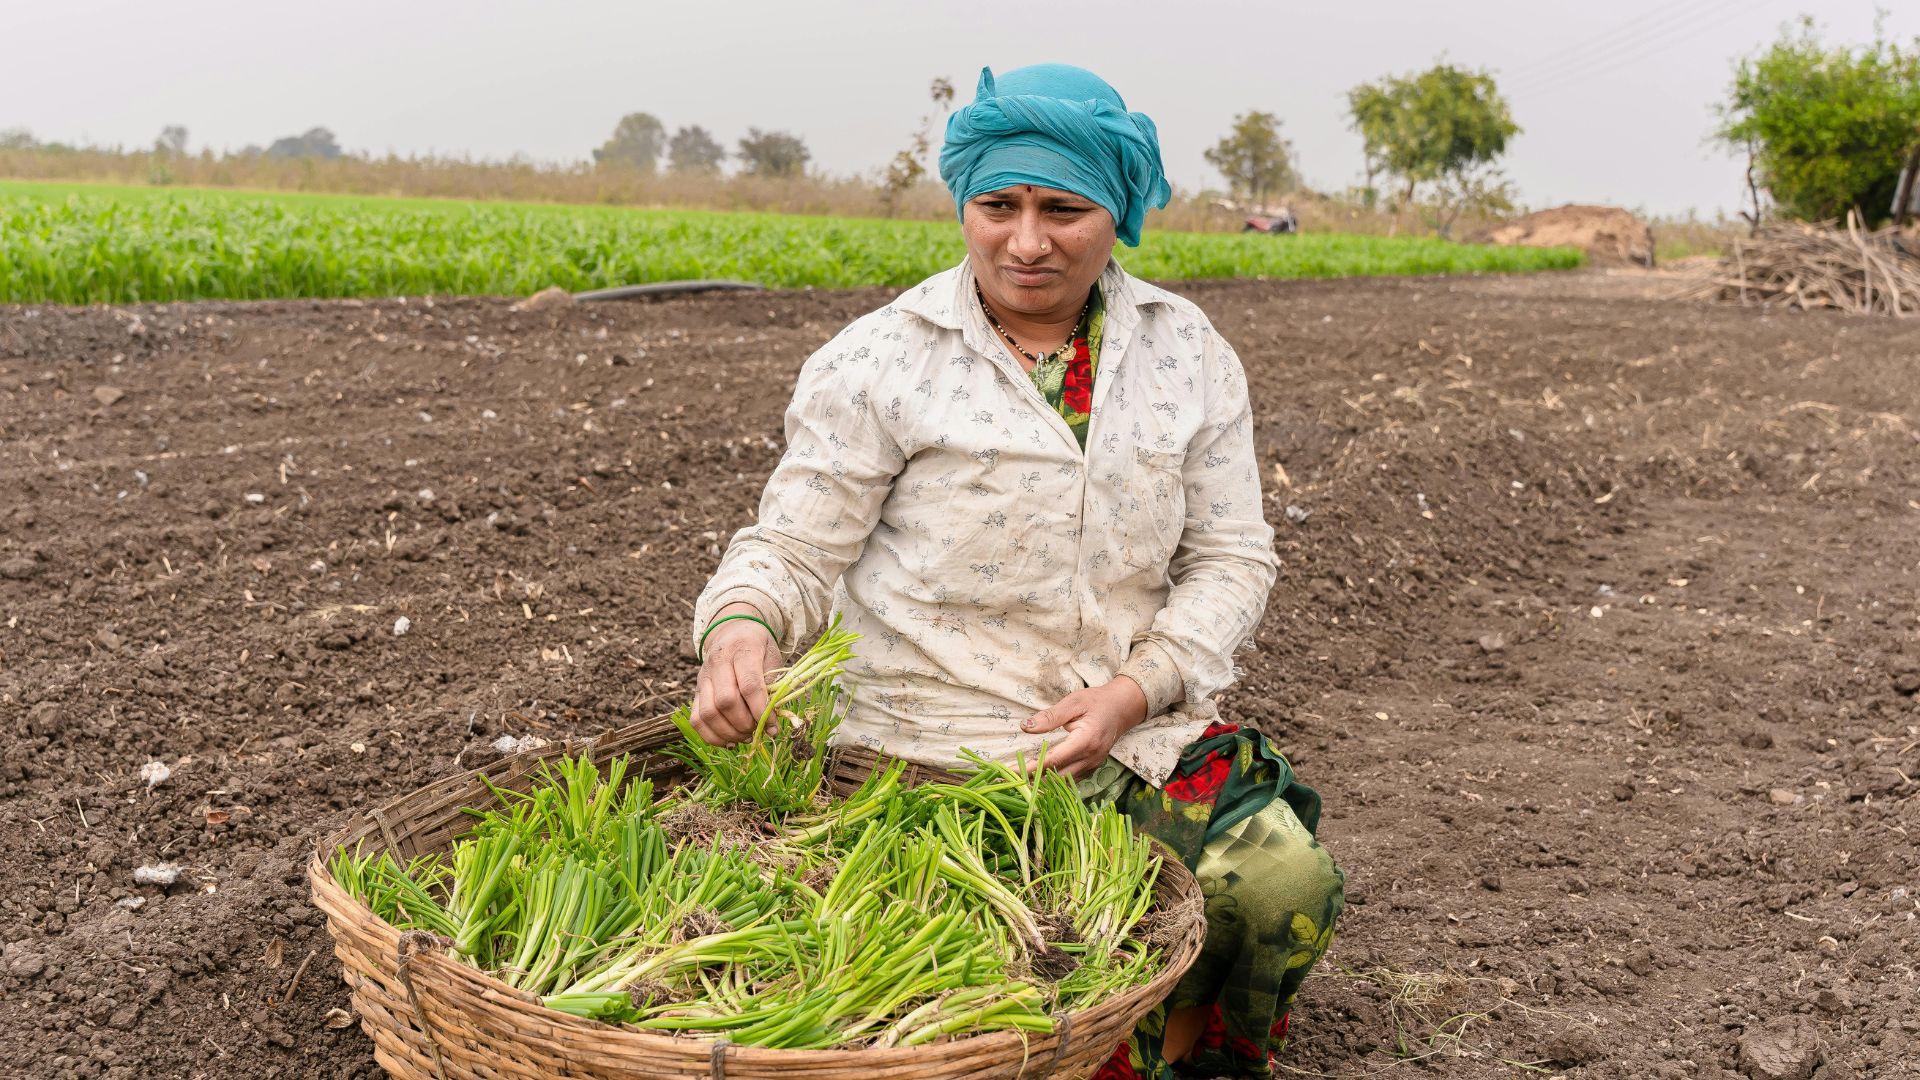
Comprehensive Analytical Study Explores India Fertilizer Market Projections
The agricultural sector serves as the historical backbone of the Indian economy, driving livelihood security for over half of the nation's populace. To sustain this vital machinery, the India fertilizer market stands as an infrastructural pillar of unparalleled importance. According to extensive market data compiled by Renub Research, the India fertilizer market size has reached a valuation of US$ 44.62 Billion in 2025. Driven by an escalating national food requirement, systemic demographic expansions, and an urgent geopolitical imperative to optimize crop yields per hectare, the market is structurally projected to expand significantly. It is anticipated to attain a market valuation of US$ 75.96 Billion by 2034. This long-term expansionary trajectory reflects a stable Compound Annual Growth Rate (CAGR) of 6.09% during the forecast timeline spanning from 2026 to 2034.
Download Free Sample Report: https://www.renub.com/request-sample-page.php?gturl=india-fertilizers-market-p.php
Technical Foundations and Contemporary Structural Outlook of Fertilizers
Fertilizers are defined as specialized organic or inorganic chemical compounds applied directly to soil substrates or plant tissues to supply one or more essential nutrient elements critical to vegetative growth, structural development, and overall agricultural yields. In standard agronomic operations, these chemical mediums fulfill the vital role of delivering primary macronutrients—predominantly nitrogen (N), phosphorus (P), and potassium (K)—alongside secondary nutrients like calcium, magnesium, and sulfur, and critical metallic micronutrients such as zinc, iron, and boron. By systematically replenishing depleted soil matrices, these compounds dramatically enhance overall soil fertility, improve post-harvest crop quality, and ensure the ongoing maintenance of complex soil macronutrient ratios. The commercial market presents these inputs across three primary product categories: highly concentrated synthetic chemical fertilizers, ecologically restorative organic fertilizers, and biologically active biofertilizers, each designed to meet distinct soil typologies and specialized crop requirements.
Within the geographic boundaries of India, fertilizers have achieved universal systemic penetration due to the country's foundational dependence on agricultural outputs to safeguard aggregate national food security. Given that a vast demographic segment relies heavily on agrarian income streams, maximizing agricultural throughput remains a critical socioeconomic priority. However, the modern Indian agricultural landscape faces structural constraints, notably a fixed baseline of arable land and varying degrees of localized soil degradation. These factors make the systematic administration of external fertilizers essential for boosting vertical crop productivity.
Furthermore, the widespread adoption of modern high-yielding variety (HYV) seeds, advanced mechanization, and micro-irrigation networks has structurally increased the native nutrient absorption capacity of domestic fields, accelerating the overall national consumption of commercial fertilizers.
Primary Microeconomic and Macroeconomic Drivers Powering Market Growth
Escalating Aggregate Food Demand and Unprecedented National Demographic Shifts
The structural expansion of the Indian fertilizer market is driven primarily by the profound demographic changes occurring across the subcontinent. In April 2023, India's population reached 1,425,775,850, officially surpassing China to become the most populous nation on Earth. Long-term demographic modeling indicates that India’s population will continue to expand, with projections suggesting a peak of approximately 1.7 billion individuals by the 2060s.
This sustained demographic expansion creates an urgent, ongoing need to scale up domestic food production. Because the total physical geographic area available for agricultural cultivation remains fixed or is gradually declining due to urban industrial encroachment, the nation must rely on vertical yield optimization. Commercial fertilizers are critical for replacing the massive volumes of nitrogen, phosphorus, and potassium extracted from the soil during intensive multi-cropping cycles. As consumer demand shifts toward nutrient-heavy food categories like cereals, high-value fruits, leafy vegetables, and pulses, the agricultural sector's reliance on high-efficiency fertilizers is projected to remain steady.
Robust Institutional Subsidization Architectures and Strategic Government Frameworks
The structural stability and growth of the Indian fertilizer market are deeply supported by comprehensive government intervention and financial subsidization policies. The Government of India directly manages a substantial fiscal subsidy apparatus targeting essential fertilizer variants—specifically urea, di-ammonium phosphate (DAP), and various complex nitrogen-phosphorus-potassium (NPK) formulations. This ensures that these vital agricultural inputs remain financially accessible to smallholder and marginal farming communities across the country.
India Fertilizer Market Sovereign Value Forecast (2025 vs 2034)

2025: ■■■■■■■■■ US$ 44.62 Billion
2034: ■■■■■■■■■■■■■■■ US$ 75.96 Billion
CAGR: 6.09% (2026-2034)
Simultaneously, state-sponsored initiatives such as the PM-KISAN Yojana (Pradhan Mantri Kisan Samman Nidhi) and the PM-Garib Kalyan Yojana provide vital liquidity support to agrarian households. This direct financial backing has been globally recognized by international organizations, including the United Nations Development Programme (UNDP), for its role in maintaining rural food security.
To address international supply vulnerabilities, the government is also actively reshaping the market through the localized commercialization of advanced nano-liquid fertilizer technologies. Strategic industrial blueprints mandate the expansion of high-tech nano-liquid production infrastructure to thirteen highly specialized manufacturing plants. This expansion aims to achieve an annual domestic production capacity of 44 crore (440 million) 500-ml bottles of advanced nano urea and nano di-ammonium phosphate (DAP), insulating the domestic market from global geopolitical supply shocks.
Modernization of Agronomic Practices and Technological Integration
The rapid integration of advanced agricultural technologies across India's rural sectors is reshaping traditional input application methods. Modern farming practices, including tractor-driven mechanical sowing, satellite-assisted precision agriculture, and automated drip fertigation systems, depend on highly calibrated, predictable fertilizer formulations.
To capitalize on these shifts, industrial research and development has focused on creating sophisticated, locally sourced input alternatives. In a major technological breakthrough, the Ministry of Mines successfully developed an indigenous water-soluble fertilizer technology. This project utilizes domestic raw materials and locally engineered processing facilities. By shifting production toward advanced, water-soluble, and specialized fertilizer options, this technology is positioned to transform India from a historical net importer into a major global exporter of highly specialized, high-efficiency agricultural nutrients.
Crucial Structural Challenges Facing the Domestic Market Environment
Systematic Nutrient Imbalances and Ongoing Soil Health Degradation
One of the most pressing structural challenges within the Indian fertilizer ecosystem is the historical imbalance in nutrient application rates, characterized primarily by the heavy over-application of traditional nitrogenous fertilizers, notably urea. This imbalance is largely driven by asymmetrical distortion within the state subsidy architecture, where fiscal price-incentives for urea have historically been higher than those allocated for phosphatic and potassic variants.
As a result, rural farming communities frequently apply over-concentrated amounts of nitrogen to their crops. Over time, this practice leads to severe soil health degradation, including soil acidification, micronutrient depletion, and a long-term decline in crop response ratios. Shifting the market toward balanced nutrient ratios remains a significant educational and structural challenge for agricultural expansion.
Deep Import Vulnerabilities and Volatile Production Cost Structures
The Indian fertilizer sector faces significant structural challenges due to its systemic reliance on international supply chains for critical raw materials, including rock phosphate, sulfur, muriate of potash (MOP), and pooled natural gas, which serves as the primary feedstock for synthetic ammonia synthesis. This structural dependence leaves domestic manufacturing operations highly vulnerable to international commodity price volatility, maritime freight disruptions, and shifting geopolitical realities.
When international energy tariffs increase, the cost of domestic production rises sharply, squeezing the profit margins of local manufacturing corporations. While state-backed financial subsidies help insulate retail prices for farmers, the escalating costs place a heavy burden on the national treasury. Consequently, reducing import dependence while ensuring affordable, timely distribution across the country remains a key challenge for market stakeholders.
Segmented Analysis of Key Nutrient Product Types
India Urea Fertilizer Market
The urea fertilizer segment continues to hold a dominant share within the Indian agricultural input market, primarily because nitrogen is the foundational building block for plant vegetative biomass. Urea is used extensively in the cultivation of major staples like wheat and paddy rice, as well as high-volume cash crops like sugarcane and cotton. The segment's strong market position is reinforced by substantial retail price subsidies provided by the Central Government, which make it highly cost-effective for farmers.
Additionally, the government's mandatory transition to 100% Neem-Coated Urea has delivered significant structural improvements. This modification slows down nitrogen release in the soil, reducing leaching losses and improving overall nutrient uptake efficiency, while successfully preventing the illegal diversion of agricultural urea into industrial manufacturing sectors.
India MOP (Muriate of Potash) Fertilizer Market
The commercial market for Muriate of Potash (MOP) is critical for meeting the potassium requirements of high-yield crops, helping to improve systemic disease resistance, optimize cellular water regulation, and enhance post-harvest product quality. MOP application is particularly vital for potassium-deficient soil zones cultivating cash crops like sugarcane, oilseeds, and various horticultural varieties.
Because India does not possess commercially viable native geological deposits of potash, this segment operates under a total reliance on international imports. Market dynamics are managed through the government's Nutrient Based Subsidy (NBS) framework, which calibrates import volumes and fiscal support to ensure steady supplies across rural retail distribution points.
Structural Distribution Channels and Organizational Models
India Cooperative Sector Fertilizer Market
The cooperative fertilizer model is a vital pillar for ensuring equitable distribution across India's vast rural interior. Led by major nationwide entities like the Indian Farmers Fertiliser Cooperative Limited (IFFCO) and the Krishak Bharati Cooperative Limited (KRIBHCO), this network utilizes thousands of localized cooperative societies to distribute inputs directly to farmers.
Beyond logistics, the cooperative sector focuses heavily on affordability, timely inventory positioning before seasonal sowing cycles, and grassroots farmer education programs. This model helps bypass speculative supply chain intermediaries, building high levels of institutional trust and ensuring reliable access for smallholder and marginal agricultural operations.
India Public Sector Fertilizer Market
The public sector operates as a direct instrument of state policy, focusing primarily on national fertilizer security and stabilizing domestic production capacity. Public sector manufacturing enterprises are mandated to produce high-volume, cost-effective chemical inputs to safeguard national food production targets. Supported by direct government capital allocations, modern technology upgrades, and natural gas allocations, these public enterprises provide a reliable production baseline that protects the wider agricultural economy from market monopolies and global supply fluctuations.
India Private Sector Fertilizer Market
The private fertilizer sector drives commercial innovation, logistics optimization, and the diversification of specialized nutrient options. Private corporations invest heavily in developing high-margin specialty fertilizers, chelated micronutrient packages, custom soil-specific formulations, and bio-stimulants. By building agile, responsive distribution networks and deploying technical agronomic field advisors, the private sector complements public and cooperative distribution channels. This active participation helps accelerate the transition toward balanced, precision-oriented crop fertilization.
Granular Regional Analysis of Major Agrarian States
Punjab Fertilizer Market
The state of Punjab stands as a highly intensive consumption hub within the national fertilizer market. Commonly recognized as the "Breadbasket of India," Punjab's agricultural model relies on high-intensity, double-cropping rotations of high-yielding wheat and rice. This model is supported by comprehensive canal and tube-well irrigation networks.
State-Level Crop & Nutrient Dynamics

Punjab          -> Focus: Wheat & Paddy Rice        -> Inputs: Intensive Urea & DAP
Uttar Pradesh   -> Focus: Sugarcane & Mixed Staples -> Inputs: Scaled Volumetric Supply
Madhya Pradesh  -> Focus: Soybeans & Pulses         -> Inputs: Growing Balanced Micro-Nutrients
Tamil Nadu      -> Focus: Intensive Horticulture    -> Inputs: High-Efficiency Specialty Blends
Because these intensive agricultural practices quickly deplete natural soil nutrients, the state maintains some of the highest per-hectare chemical fertilizer consumption rates in the country, focused mainly on Urea and DAP. To address the long-term sustainability challenges of this intensive model, current market trends are shifting toward state-sponsored soil testing programs and precision application techniques.
Uttar Pradesh Fertilizer Market
Uttar Pradesh represents the largest volumetric consumption market in India, driven by its expansive geographic area under active cultivation and a highly diverse crop profile. The state's agricultural output includes massive volumes of wheat, paddy rice, pulses, oilseeds, and a dominant share of national sugarcane production.
Backed by a dense rural population and an extensive network of retail distribution points, the state requires a steady, high-volume supply of diverse fertilizer products. Ongoing state initiatives focus on expanding the distribution of Soil Health Cards to help farmers transition toward balanced nutrient applications and reduce input waste.
Madhya Pradesh Fertilizer Market
The fertilizer market in Madhya Pradesh is expanding rapidly, supported by growing crop diversification and significant improvements in rural irrigation infrastructure. The state has established itself as a leading producer of commercial soybeans, pulses, wheat, and oilseeds, which require specific balanced inputs of phosphorus, sulfur, and potassium. The steady rollout of state-backed agricultural extension programs has helped farmers optimize their nutrient applications, leading to strong growth across the region's complex and phosphatic fertilizer segments.
Tamil Nadu Fertilizer Market
The fertilizer market in Tamil Nadu is characterized by advanced, high-intensity farming techniques and a strong focus on high-value cash crops, including rice, sugarcane, cotton, and extensive horticultural varieties. Faced with fixed limits on arable land, local farming operations focus heavily on maximizing vertical productivity per acre. This emphasis has driven strong regional demand for advanced fertilizer alternatives, including water-soluble options, micronutrient mixtures, and specialized drip-fertigation inputs designed to maximize nutrient utilization efficiency.
Detailed Corporate Landscapes and Key Market Competitors
The India fertilizer industry features a diverse mix of large public undertakings, deeply rooted cooperative federations, and agile, innovation-focused private corporations. The top tier of the corporate market includes five major enterprises:
-
Nagarjuna Fertilizers and Chemicals Ltd. (NFCL): A major private-sector player with a strong footprint across southern India, known for its extensive manufacturing operations and deep penetration into micro-irrigation and customized nutrient solutions.
-
Chambal Fertilisers & Chemicals Ltd.: One of the largest private-sector urea manufacturers in India, operating advanced, highly efficient production facilities in Gadepan, Rajasthan, and maintaining an extensive distribution network across northern and western states.
-
Rashtriya Chemicals & Fertilizers Limited (RCF): A leading public-sector enterprise under sovereign ownership, producing a diverse portfolio that includes Ujjwala Urea, Suphala complex fertilizers, and various specialized industrial chemicals.
-
National Fertilizers Ltd. (NFL): A premier public-sector producer and the nation's second-largest manufacturer of urea, driving major capacity expansions and leading rural development initiatives through its extensive retail network.
-
Coromandel International Ltd.: A private-sector leader in phosphatic and complex fertilizer formulations, widely recognized for its integrated crop-nutrition portfolios, specialized nutrients, and an extensive network of rural retail centers (Gromor Centers).
Analytical Framework: Corporate Viewpoints
┌─────────────────────────────────────────────────────────────┐
│                 5-POINT CORPORATE ANALYSIS                  │
├───────────────┬──────────────────────────────┬──────────────┤
│ 1. Overviews  │ Corporate structures & assets│ Operational  │
├───────────────┼──────────────────────────────┤ Capabilities │
│ 2. Leadership │ Key executives & management  │ and Market   │
├───────────────┼──────────────────────────────┤ Positioning  │
│ 3. Innovation │ Recent tech & capacity shifts│ For All Top  │
├───────────────┼──────────────────────────────┤ Competitors  │
│ 4. Strategy   │ Granular SWOT Analysis       │              │
├───────────────┼──────────────────────────────┤              │
│ 5. Financials │ Comprehensive revenue metrics│              │
└───────────────┴──────────────────────────────┴──────────────┘
Final Thoughts
The India fertilizer market is undergoing a structural transition, shifting from a historical focus on sheer volume to a highly calibrated model centered on nutrient efficiency, technological innovation, and long-term environmental sustainability. The market projections compiled by Renub Research—indicating an expansion to US$ 75.96 Billion by 2034—reflect more than simple volumetric growth. This trajectory captures a fundamental shift toward advanced, high-efficiency agricultural inputs.
As the country balances the urgent need to feed the world's largest population with the necessity of preserving its foundational soil health, the future of the market will increasingly belong to specialized, intelligent nutrient solutions. The rapid adoption of indigenous water-soluble technologies, the expansion of regional nano-liquid production facilities, and the ongoing stabilization of direct-benefit subsidy frameworks are combining to create a resilient, self-directed agricultural ecosystem. For corporate manufacturers, cooperative distribution networks, and policy architects alike, the focus must remain on advancing balanced crop nutrition to ensure long-term, nationwide food security.

 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
