 About Urh Social
 Terms of Service
 Privacy Policy
 Contact
Automotive Telematics Insurance Market Growth and Forecast
Market Overview
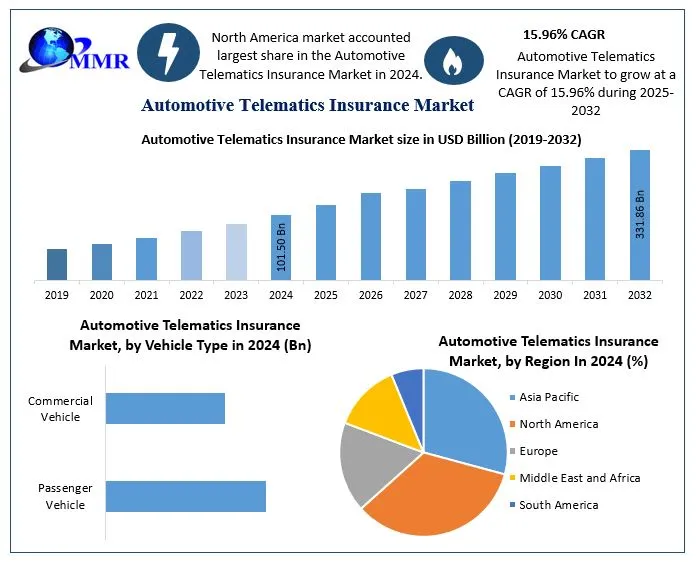
The Automotive Telematics Insurance Market is entering a period of strong expansion as insurers increasingly use connected-vehicle data, artificial intelligence (AI), Internet of Things (IoT) technologies, smartphones, and real-time analytics to develop personalized insurance products. According to Maximize Market Research, the global Automotive Telematics Insurance Market was valued at approximately USD 101.50 billion in 2024 and is projected to grow at a CAGR of 15.96% from 2025 to 2032, reaching nearly USD 331.86 billion by 2032.
Automotive telematics enables insurers to collect and analyze information such as mileage, vehicle location, acceleration, braking, cornering, driving time, and other driving-behavior indicators. This information supports usage-based insurance (UBI), including pay-as-you-drive and pay-how-you-drive models, allowing premiums and discounts to be increasingly aligned with actual vehicle usage and driving behavior. The technology can also support accident detection, claims management, vehicle recovery, preventive safety services, and fleet management.
The increasing penetration of connected vehicles is a major growth driver. Automakers are increasingly integrating embedded connectivity and data communication systems into passenger vehicles, creating a large stream of real-time vehicle information that can potentially be utilized by insurers. MMR identifies improved fleet-management efficiency, increasing demand for vehicle safety, and growing adoption of AI, IoT, and 5G as important factors supporting market expansion.
Another significant opportunity is the development of AI-powered risk assessment. Telematics allows insurers to supplement traditional demographic and historical data with behavioral information, potentially improving risk segmentation and enabling more personalized insurance products. Smartphone-based telematics is also lowering the need for dedicated hardware, while embedded vehicle systems are creating opportunities for direct connectivity between automakers, insurers, and customers.
U.S. Market Trends and Investment in 2025
The United States remains a major center for automotive telematics insurance because of its large automobile insurance market, high vehicle ownership, established insurance industry, and advanced connected-vehicle infrastructure. In 2025, UBI continued to receive attention from insurers and technology companies. J.D. Power reported that 17% of insurers offered UBI programs to shoppers in 2025, compared with 15% in 2024, indicating a modest increase in availability. At the same time, investment continued in technology-driven underwriting. In September 2025, Japan's ITOCHU Corporation announced a financial and business partnership with U.S.-based MOTER Technologies and agreed to purchase newly issued shares in the telematics-insurance software company. ITOCHU cited expanding UBI adoption in the U.S. following the growth of connected cars and advanced driver-assistance systems. Regulatory activity is also evolving: New York introduced legislation in 2025 addressing insurers' use of telematics and UBI, including a consent-based framework.
Request To Free Sample of This Strategic Report ➤ https://www.maximizemarketresearch.com/request-sample/73659/
Market Segmentation – Largest Segment
According to Maximize Market Research, the Global Automotive Telematics Insurance Market is segmented primarily by Vehicle Type and Device Type.
1. By Vehicle Type
-
Passenger Vehicle
-
Commercial Vehicle
Passenger vehicles held the largest market share in 2024, supported by increasing adoption of pre-installed telematics devices and usage-based insurance (UBI). Commercial vehicles are projected to grow at the highest CAGR of 16.2% during the forecast period due to increasing adoption of UBI by fleet owners.
2. By Device Type
-
Hardwired
-
On-board Device (OBD)
-
Smartphone
-
Embedded
3. By Region
-
North America
-
United States
-
Canada
-
Mexico
-
-
Europe
-
UK
-
France
-
Germany
-
Italy
-
Spain
-
Sweden
-
Austria
-
Turkey
-
Russia
-
Rest of Europe
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
ASEAN
-
Rest of APAC
-
-
Middle East & Africa
-
South Africa
-
GCC
-
Egypt
-
Nigeria
-
Rest of ME&A
-
-
South America
-
Brazil
-
Argentina
-
Colombia
-
Rest of South America
-
Competitive Analysis
MMR identifies a broad competitive landscape comprising insurers, telematics specialists, automotive technology companies, connectivity providers, and software developers. The public MMR report identifies the major participants but does not publish individual company market-share percentages; therefore, an exact ranking of the “top five by global share” cannot be independently established from the public report. Five prominent companies from the identified competitive landscape are The Progressive Corporation, AXA Group, Octo Telematics, Continental AG, and Robert Bosch GmbH.
The Progressive Corporation has developed its Snapshot UBI program around driving behavior and mileage. Its current system can operate through a mobile application or plug-in device and evaluates factors such as hard braking, acceleration, phone use, and driving patterns. Progressive reports that Snapshot customers who earn a discount save an average of $328 annually, demonstrating the continued use of behavior-based pricing as a customer-engagement mechanism.
AXA Group is participating in the expansion of connected insurance models across Europe. A notable 2025 development was the relaunch of Stellantis Finance & Services' DRIVE & CONNECT connected-auto-insurance product in partnership with AXA France and AssurOne. The redesigned offering became available across Stellantis vehicles and provides premium reductions based on driving behavior.
Octo Telematics continues to develop telematics, IoT, data analytics, and risk-modeling capabilities. In November 2025, OCTO announced a partnership with Liberty Rider focused on connected motorcycle safety, including advanced detection and automatic crash-detection capabilities. Such technologies can expand telematics beyond pricing into accident prevention and emergency assistance.
Continental AG and Robert Bosch GmbH represent the automotive technology side of the ecosystem, where connected-vehicle electronics, sensors, software, and vehicle-data infrastructure can facilitate integration between vehicles and insurance services. MMR includes both companies among the key players in the market.
Regional Analysis
United States: North America is expected to dominate the global automotive telematics insurance market, with the United States representing its principal market. The country's large auto-insurance base, connected-vehicle penetration, telematics adoption, and state-level development of UBI programs support continued growth. MMR specifically identifies North America as the leading region.
United Kingdom: The U.K. benefits from an established motor-insurance industry and long-standing adoption of black-box and app-based insurance models. Continued development of connected vehicles and data-driven underwriting provides opportunities for telematics insurance.
Germany: Germany is identified by MMR as Europe's leading country for automotive telematics. Its strong automotive manufacturing base, connected-car development, and concentration of major OEMs provide an important ecosystem for vehicle-data-based insurance services.
France: France represents an important European market where connected insurance is increasingly linked with vehicle manufacturers and insurers. The 2025 expansion of the Stellantis-AXA DRIVE & CONNECT offering illustrates how OEM-insurer partnerships can broaden telematics insurance availability.
Japan: Japan has a mature connected-car ecosystem and a history of integrating telematics into insurance. Toyota and Aioi Nissay Dowa Insurance developed telematics insurance using connected-car driving data, including speed, acceleration, braking, mileage, and safety-driving scores.
China: China provides significant long-term growth potential because of its large automotive market, expanding connected-vehicle ecosystem, and increasing use of vehicle data. Research published in 2025 using data from a major Chinese auto insurer examined telematics-based UBI pricing and customer-retention models, demonstrating continued development of data-driven insurance approaches.
Across Europe, regulatory developments are also shaping the market. The EU Data Act began applying in September 2025, establishing rules intended to increase user access to data generated by connected products, including cars, while supporting data-driven innovation.
Request To Free Sample of This Strategic Report ➤ https://www.maximizemarketresearch.com/request-sample/73659/
Key Players
1. Octo Telematics
2. CalAmp, Agero Inc
3. AXA Group
4. Cambridge Mobile Technology
5. Intelligent Mechatronic System
6. The Floow Ltd
7. The Progressive Corporation
8. TomTom
9. Trakm8 Group
10. TrueMotion Inc.
11. Robert Bosch GmbH
12. AT&T INC.
13. Continental AG
14. LG Electronics
15. Verizon
16. Harman International
17. Aptiv PLC
18. Visteon Corporation
19. Magneti Marelli CK Holdings
20. Webfleet Solution
Conclusion
The Automotive Telematics Insurance Market is positioned for substantial expansion as insurance moves toward more data-driven, personalized, and connected business models. The projected increase from USD 101.50 billion in 2024 to nearly USD 331.86 billion by 2032 reflects the growing commercial importance of connected vehicles, UBI, AI-powered risk analytics, and real-time vehicle data.
The major opportunity lies in combining embedded vehicle connectivity, smartphone telematics, AI/ML risk modeling, 5G connectivity, and advanced driver-assistance data into integrated insurance platforms. Insurers that can transform telematics data into transparent pricing, safer-driving feedback, faster claims processing, and value-added mobility services may find significant opportunities for market expansion. At the same time, privacy, consent, cybersecurity, and regulatory compliance will remain critical considerations as the volume of vehicle-generated data increases.
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
Contact Us
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
[email protected]

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek